Monday, 8 June 2020

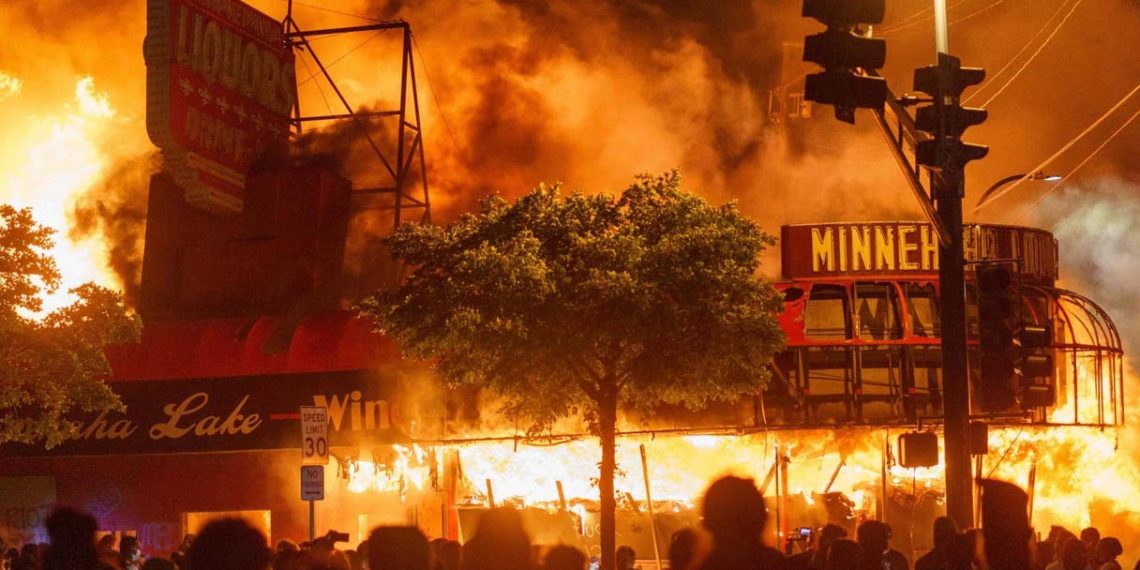
Clickbait or Fact: Riots and Your Health (and maybe life)

So here's a pretty relevant question:

Does your health insurance cover your expenses if you're injured in a riot?

And what, precisely, does "in" mean here?

As we learned from last week's post on homeowner's insurance, the definition of a word is often (usually? always?) relevant when we're speaking of what's covered and what's not.

Okay Henry, what's your point?

Well, FoIB Bill M sent along a link to this little item:


And indeed, this appears to be very much the case.

In researching this post, I learned a few things, myself:

First, as usual, consulting the exclusions of a policy is generally pretty helpful in determining whether or not you have a valid claim (we'll circle back to this).

Second,the type of plan you have matters: individual versus group plans, even from the same company, may treat the issue differently (and indeed, one such carrier's individual plan has no exclusion for riot-related claims, while their group plans do).

Third, and I think this may the be the most important distinction of all: among those plans which exclude riots (and/or civil unrest), some exclude only those injuries resulting while an active an active participant, while others just exclude any and all riot-related expenses. This is important, as we've seen innocent folks pulled from their cars and others hit in the head by bricks thrown at them from yards away.

Oh, and what about other kinds of insurance? Well, turns out that, in general:


·         Life insurance (no longer) has no such exclusion, but Accidental Death riders may
·         Some individual disability plans do exclude riots/civil unrest, and some don't
·         Group plans seem to ...


And what about the Big Daddy, Medicare? Well, that also kinda depends. According to Kaiser Health News, "Medicare, the insurance program for people age 65 and older and people with disabilities, doesn’t have these exclusions."

BUT: Medigap policies (Supplements) typically follow Medicare's lead on what's covered or not, but that doesn't seem to be universal. For example, Viva Medicare Select Plus says:

"... the following items and services are not covered by ViVa Medicare Plus Select:47. Services required as a result of participation in a riot"
Hunh.

As usual, check with your own agent or carrier (or simply look up the exclusions in your policy itself). In this case, it really does pay to be informed.

[Special IB thanks to Brian D, Tana H, Beth D, Fred W, Michael B, Roger D, and co-blogger Bob V]


from InsureBlog https://ift.tt/3dVjwIA

Friday, 5 June 2020

Homeowner's Heads' Up

Many of us have relatives who've been moved, for whatever length of time, into a nursing home.

Or, for estate planning purposes, put our home in a trust.

Or taken a new job in a new city three states away.

Yes, Henry, this happens all the time. What's your point?

Well:

"A couple in Georgia bought a “fixer upper” home that was being renovated by their contractor son before their occupancy began. During this three to four month period, they stayed in an apartment. Near the end of the renovation, the house suffered a $186,000 fire loss. The insurance company denied the claim under the homeowners policy."

All of these examples, both hypothetical and real-life, involve a little-known, and even lesser understood, insurance policy phrase "residence premises." And just what is "resident premises?" Well, it's typically defined as "the dwelling “where ‘you’ reside.” Okay, that seems straightforward enough, as long as we all agree on what "reside" means.

Hunh?

Well, when I leave for work in the morning on my long, arduous 6 minute commute, I may not be present in the house for the next few hours, but I still reside there. Likewise, when we take a week-long family road trip, we still technically reside there. It becomes a little fuzzier for snowbirds, but this is common enough that it's not really an issue.

As FoIB (and P&C Guru) Bill M advises, we begin to run into problems when we look at the terms terms 'occupancy' and 'ownership:'

When we assign ownership of our home to the Smith Family Trust, even though we still live (reside) there, we need to notify our insurance company, because the ownership has changed (although I would note that the risk has not, but then, one should never conflate 'common sense' with 'insurance'). When we maintain ownership, but actually move out and far away, this changes the nature of the risk, and we need to - you guessed it - notify our insurance carrier, or at least have a genuine heart-to-heart with our agent about what they advise.

What one should not do is simply pretend there's no issue or potential problem, because it's a lot easier (and cheaper) to address it before a claim and potential lawsuit.

#WordToTheWise


from InsureBlog https://ift.tt/2MwBULV

Thursday, 4 June 2020

Sigh: Another Riot-related P&C Post

So we know that our homeowner's and business insurance policies likely cover damage from the on-going riots, but what about all those cars we've seen being bashed and burned?

Well, we reached out to FoIB (and P&C Guru) Bill M for the skinny on that:

First, this is a covered claim, assuming that you have comprehensive coverage (comp, as opposed to collision or liability), and of course subject to the deductible.

And I found this interesting: if you have rental reimbursement coverage on the vehicle, that comes into play, as well, so that you're not even further inconvenienced.

Bill also confirmed that a business auto policy would also cover this, as long as one had the aforementioned comp coverage.

If the damage appears to be minor, it may make sense to get an estimate before turning in a claim, especially oif it's under (or just over) your deductible.

Thanks, Bill!


from InsureBlog https://ift.tt/3cv2I9R

Wednesday, 3 June 2020

Life insurance matters

Our friends at the Cincinnati Insurance blog have a helpful new post up answering some common questions about life insurance.

For example:

"How much do I need? What does life insurance do? How much will it cost? Where do I begin?"

As the author notes,while these are important questions, they're not particularly difficult ones, they just require a little planning and honest soul (and checkbook) searching.

Good stuff!


from InsureBlog https://ift.tt/2Mn5C62

Tuesday, 2 June 2020

Our Friend and Erie Insurance doing good


We've posted before about how carriers are giving back to their clients:

"In general, insurers that represent four out of five auto insurance policies sold in the United States have offered to refund some portion of driver premiums."

But Erie's taken it up a notch, by partnering with local agents to support communities. In this case, FoIB (and resident P&C Guru) Bill M has chosen KIND (Kinds in New Directions) as his worthy cause:

"KIND is a free, inner-city, after-school and summer learning program."

As Bill explains, KIND provides young people with help and guidance with academic classes and life-skills (such as sewing and nutrition). Kudos!

If you'd like to help, just click here.


from InsureBlog https://ift.tt/2XT7bhB

Monday, 1 June 2020

Riots, Unrest, and Insurance: What Gives?

Given the current circumstances, it seems valuable to revisit a post we did a half-decade ago when Baltimore went up in flames. The question then, as now, was whether or not the property destruction would likely be covered under one's insurance. Of course, it gets a bit more nuanced, as coverage will differ slightly by locale and policy form. I reached out to FoIB (and P&C Guru) Bill M, who reminded me that a key distinction lies with the difference between terrorism (generally excluded) and civil unrest (generally covered).

He also confirmed that coverage is likely under both homeowners and commercial lines policies. As he so often instructs us: look to the exclusions for the best answers.

And with that out of the way, here's what we wrote in '15, and which applies today, as well:

Homes, businesses and cars have been burned, looted and otherwise damaged, leaving owners wondering what, if any, insurance payments they can expect.

The Insurance Information Institute (III) has helpfully published a media advisory confirming that, generally speaking, such damage is considered a covered event, and claims will likely be honored:

"Auto, homeowners, and business insurance policies generally include coverage for property losses caused by riots and civil commotions, such as those occurring this week in Baltimore ... Standard business property insurance policies provide coverage for the structure of the building as well as the contents inside"


Whew!

As always, be sure to check with your own carrier to confirm whether or not these exposures are, in fact, covered.


from InsureBlog https://ift.tt/36Oerzj

Friday, 29 May 2020

A Plea for Help

Our good friend Chris Van B is helping to raise funds for the Artemis Center for Alternatives to Domestic Violence, a really noble cause, especially with domestic violence apparently on the rise as a result of the lock-downs. The Artemis Center, in Dayton (OH) "empowers survivors of domestic violence to make decisions and choices that will establish and maintain safety for themselves and their children. By working collaboratively with other community services, Artemis Center advocates are able to coordinate needed services."

This is especially necessary in these uncertain times, and one of Chris' vendors is offering to match contributions up to a total of $1,000. But the clock is running out on that offer.

Please click here if you can spare a few dollars for a very worthy cause. Or, you you prefer to send a check, just drop us an email for details.

Thank you!


from InsureBlog https://ift.tt/2M6QsSt